

Middle East Tensions Fuel Fresh Mortgage Rate Volatility
Markets are pricing in multiple rate hikes, but the outlook relies heavily on a single unpredictable geopolitical risk.
18 September 2026
Whether they realise it or not, anyone on a fixed-rate mortgage is paying for interest rate movements that may never happen.
That’s because deals are priced off swap rates, which are based on what investors think the Bank of England (BoE) will do next rather than decisions it has already taken.
The release of fresh economic data this week highlighted a growing disconnect between those market expectations and the supporting evidence. For anyone trying to anticipate the future path for mortgage rates, the crystal ball became even murkier.
The five-year swap rate topped 4.7% on Tuesday, sparked by a worsening security situation around the Strait of Hormuz, as we explored here.
It was the highest rate since September 2023, when stubborn inflation and strong wage growth underpinned the case for rate rises.
Today, an expectation of four or five hikes by the end of next year appears to be relying more heavily on guesswork.
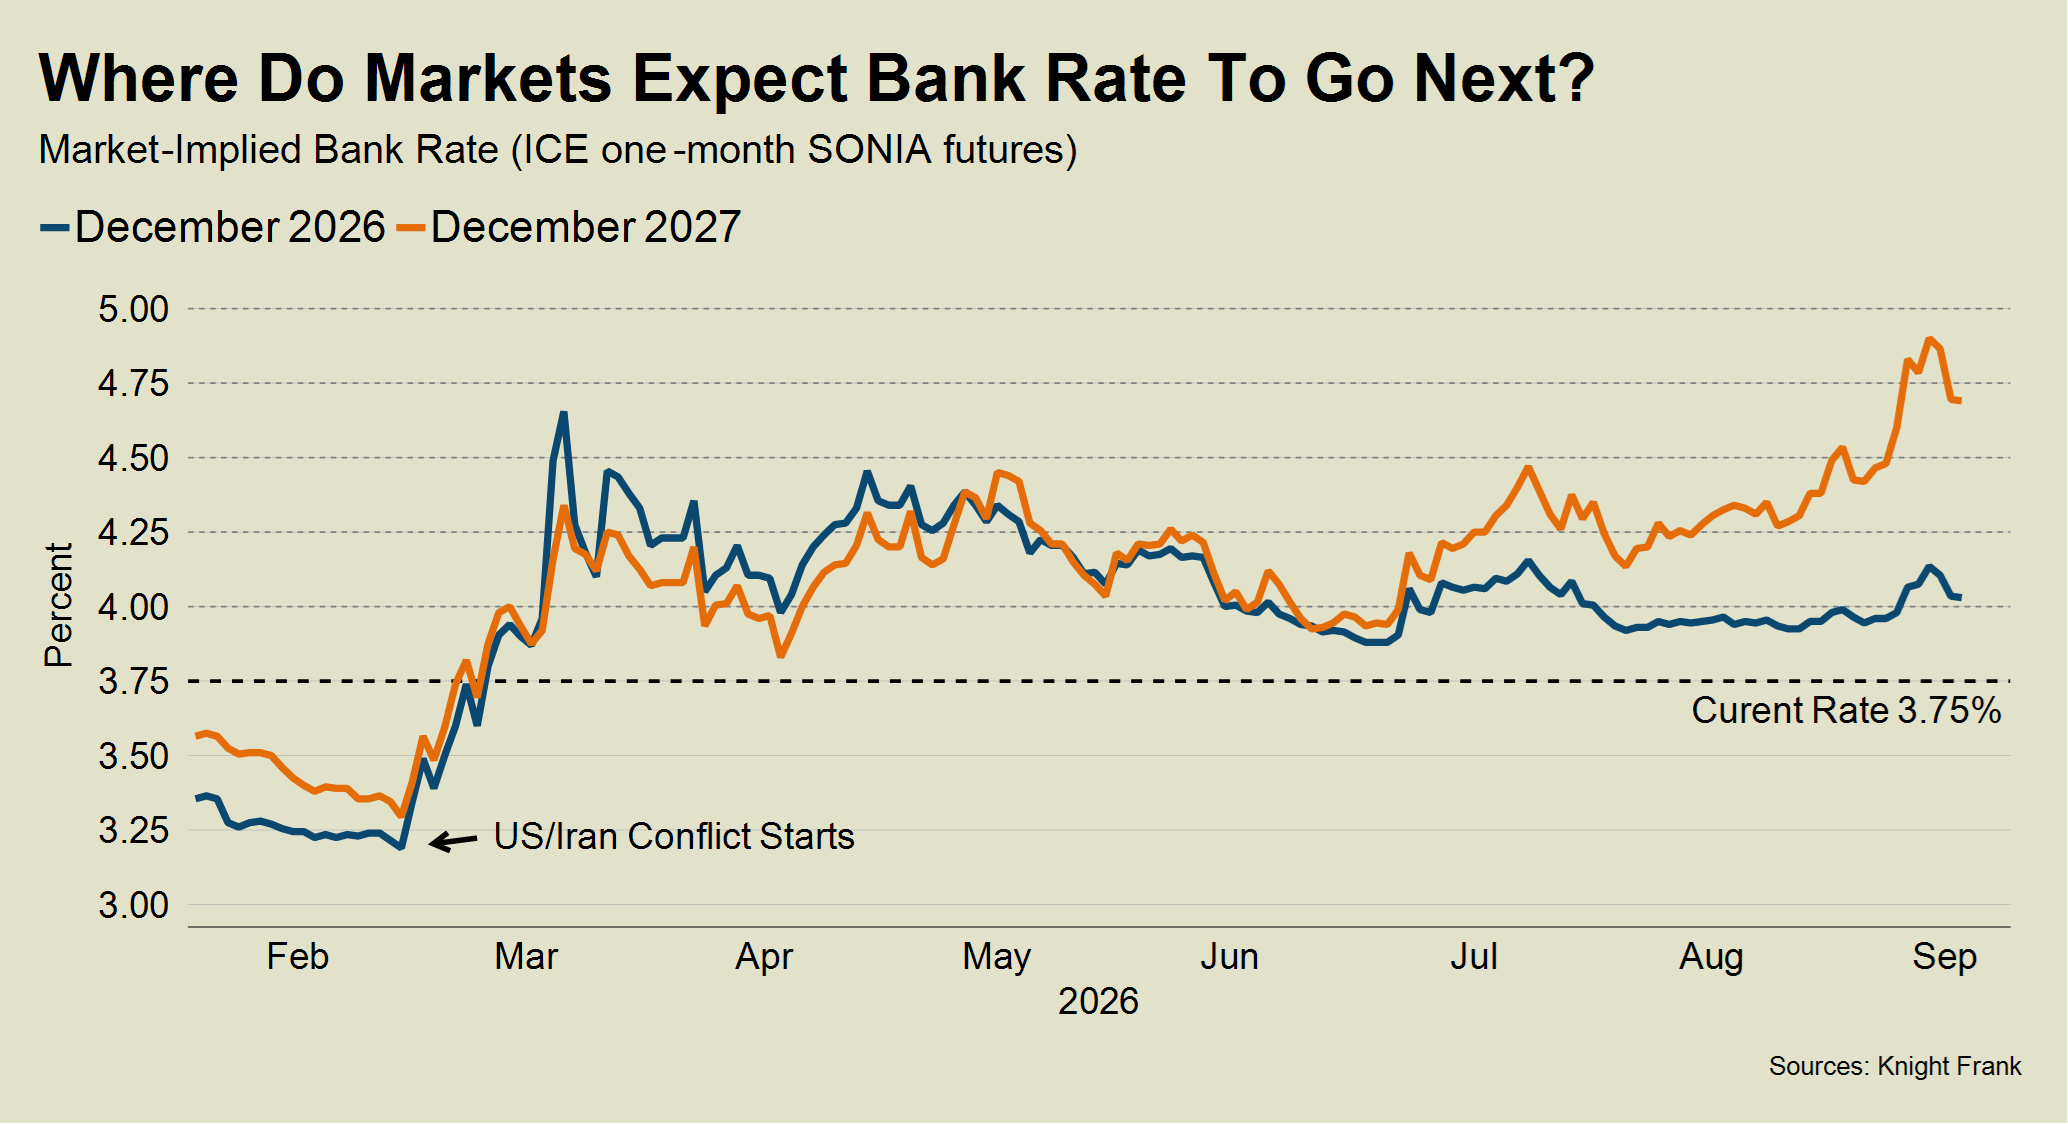
The chart shows where financial markets believe Bank Rate will be at the end of 2026 and 2027 and how that has changed since February.
The assumption is based largely on higher energy prices arising from the Middle East conflict, but there have been few signs so far that rising oil and gas prices are feeding through into UK inflation.
Soft Data
Unchanged readings for UK services and core inflation on Wednesday followed soft labour market data on Tuesday.
The lack of inflationary signals underlines how the short-term outlook for fixed-rate mortgages, which account for almost 90% of lending, currently hinges more on how the Middle East conflict unfolds than familiar economic fundamentals.
Given how higher rates have curbed prices and transactions so far this year, the outlook for the wider housing market also depends on whether military tensions escalate or recede.
It is an added layer of frustration for anyone buying or re-mortgaging. Daily oil price fluctuations will tell you more, for now, about the direction of travel for mortgage costs than monthly jobs or inflation data.
Either way, lenders have been raising rates in recent days, which means more borrowers have been taking out tracker mortgages as a result, said Simon Gammon, managing partner of Knight Frank Finance. Trackers are priced at a fixed margin above Bank Rate.
With many tracker mortgages priced at around 4% and fixed-rate deals at approximately 4.75% and up, you would need several rises from the Bank of England to close the gap.
Five Hikes
So, do five hikes by the end of 2027 even feel plausible?
“Nobody I’ve spoken to, not even the most hawkish strategists, seriously thinks the Monetary Policy Committee will deliver five hikes by the end of next year,” said market analyst Michael Brown. “A hike in November is plausible, if only to prevent the Bank of England from being seen as ‘behind the curve’ compared to their peers. Beyond that, energy prices and the potential for second-round inflationary effects will be the key policy drivers.”
While the Federal Reserve and European Central Bank (ECB) have raised rates this month, the BoE held rates at 3.75% on Thursday, as concerns about stifling growth outweighed inflation fears. The ECB also started September with a rate of 2.25%, giving it wider scope to hike.
Michael thinks traders have also priced in numerous rate hikes after paying the price for underestimating the initial impact of the conflict in March. In other words, the fear of another inflation spike is itself putting upward pressure on mortgage rates, which makes the trajectory harder to predict.
The more volatile outlook means mortgage rates could theoretically fall faster than they did from their highs in 2023. However, any decline would be tempered by the fact other global forces are putting upward pressure on borrowing costs, as we explored last week.
What the BoE does next matters beyond financial markets and mortgage holders, of course. The recent rise in borrowing costs has also made the position of Chancellor John Healey more uncomfortable ahead of the Budget next month, which I will explore in more detail next week.
Sign up to Knight Frank Research.
