

Industrial Outdoor Storage (IOS) and the Defence sector
Defence as a Driver of IOS Demand
22 September 2026

The expansion of UK defence spending is expected to create a modest but potentially important source of demand for Industrial Outdoor Storage (IOS) and low-density industrial space. While direct demand from the Ministry of Defence (MOD) and major defence contractors is likely to remain limited, increased expenditure should support activity across a wider ecosystem of logistics providers, specialist manufacturers, maintenance operators and construction contractors.
With defence spending expected to rise over the coming years, requirements for manufacturing, storage and distribution space are likely to increase across key defence clusters and logistics corridors. However, much of this activity will remain concentrated within secure MOD estates or occupier-controlled facilities, limiting direct opportunities for traditional IOS investors. Core defence operations are typically building-led, reflecting the need for secure environments, controlled processes and protected inventory.
As a result, demand is expected to focus on secure, self-contained sites and low-density formats that combine operational buildings with extensive yard space. These low-density industrial formats provide a closer fit with occupiers requiring both operational accommodation and external storage, while offering the flexibility needed to support a range of logistics, engineering and maintenance activities.
Sources of Demand
Opportunities for IOS are concentrated within the wider defence supply chain rather than core defence manufacturing. Demand is most likely to emerge across three broad areas.
Construction and infrastructure delivery will generate temporary requirements for laydown, storage and staging space as defence programmes and estate modernisation projects progress. These uses include contractor compounds, equipment storage and materials handling associated with major project delivery.
Logistics and distribution linked to the defence sector is likely to prove a more meaningful source of demand. Defence activities require the movement, storage and maintenance of equipment, components and materials across increasingly complex supply chains. This is particularly relevant within port locations and strategic logistics corridors where operational requirements favour secure sites with strong transport connectivity.
Supply-chain manufacturing, particularly among Tier 2 and Tier 3 suppliers, may also generate requirements for external storage and yard space. Unlike high-value precision manufacturing, which is typically carried out in enclosed environments, heavier industrial processes can often accommodate outdoor storage as part of their operating model.
Taken together, this demand is likely to be indirect and distributed across a broad ecosystem of occupiers rather than concentrated within a small number of major defence users. The growing emphasis on supply chain resilience and distributed logistics networks is expected to reinforce this trend, supporting demand for strategically located industrial sites that can accommodate storage, servicing and logistics functions.
The defence supply chain
The defence supply chain is likely to play a central role in translating increased defence spending into real estate demand and IOS demand specifically, particularly through third-party logistics (3PL) and specialist operators, who support procurement, storage, distribution and maintenance activities.
There are integrated/large scale provides such as Leidos, Kuehne+Nagel, TVS Supply Chain Solutions and Agility manage large-scale, multi-site logistics operations under programmes such as the Logistics Commodities & Services Transformation (LCST) Programme. Operators including GXO and Wincanton also provide warehousing, distribution and manufacturing support across national networks. Alongside these are more specialised, high-security operators focused on controlled and sensitive goods such as weapons or explosives. These include CTS Logistics, ICL, Streamline and Shipping International, and Casper Defence. These operators typically require secure, self-contained sites with specific operational and regulatory characteristics, often aligning with IOS or low-density industrial formats.
Recent market activity reflects the growing importance of supply chain resilience. The formation of the Torus Defence Supply Chain alliance by Amentum, GXO, Accenture and A.P. Moller–Maersk highlights a shift towards integrated, scalable defence logistics platforms. At an operational level, contracts such as GXO’s support for BAE Systems’ shipbuilding operations on the Clyde demonstrate how these requirements translate into distributed demand across a network of warehousing and yard-based facilities in Scotland’s Central Belt.
Property Requirements
Defence-related occupiers will often have specialised requirements. Site security and self-containment are likely to be particularly important, alongside heavy-duty surfacing, efficient HGV circulation and access to major road, port or rail infrastructure. Depending on the nature of the activity being supported, individual occupiers may also require more bespoke operational specifications.
Demand may favour large-scale or remote sites that can offer strong security, rather than small urban sites. Hybrid industrial formats that bridge the gap between conventional warehouses and traditional IOS assets may also be in demand. Investors should therefore expect demand to focus on a relatively narrow subset of the wider open storage market.
Where Will Demand Materialise?
Defence-related demand is expected to be highly location-specific. The strongest opportunities are likely to emerge where defence activity coincides with established industrial and logistics markets, providing both occupier depth and long-term liquidity.
Three broad location types appear most relevant. First, energy, port and munitions locations such as Teesside, Grangemouth and Milford Haven are well positioned to support project-led storage and handling requirements. Secondly, major manufacturing centres, including locations such as Barrow and Derby, may generate demand associated with contractors and supporting logistics functions, although most core activity will remain within secure occupier-controlled estates. Finally, large multi-sector industrial markets such as the Midlands, North West and West of England are likely to offer the most consistent opportunities because defence-related demand is supplemented by a much broader occupier base.
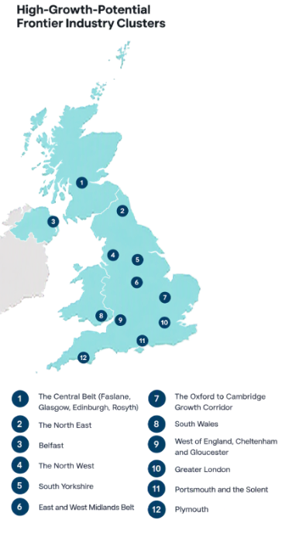
The UK's principal defence clusters are shown below. However, not all of these will generate IOS demand.
Source: UK Government’s Defence Industrial Strategy 2025
The West of England, Scotland's Central Belt, the North West and the Midlands appear particularly attractive, combining defence activity with deep manufacturing, engineering and logistics markets that support occupier depth and liquidity.
Bristol and the wider West of England, including Cheltenham and Gloucester, benefit from a diverse aerospace, defence and cyber cluster that generates demand for storage and low-density industrial space linked to large machinery, bulk materials and specialist components. While Scotland's Central Belt combines naval shipbuilding with major assets at Faslane and Rosyth, supporting demand for secure laydown, staging and materials storage, alongside a strong advanced manufacturing and logistics base.
In the North West, military aircraft production, shipbuilding and weapons systems create recurring requirements for logistics and storage space. The Midlands combines defence manufacturing, engineering and communications capabilities with one of the UK's deepest industrial occupier markets, while South Yorkshire's advanced materials and heavy engineering strengths, centred on Sheffield Forgemasters and the AMRC, provide additional growth potential.
Activity within the MOD estate, including base modernisation and housing delivery, may also generate construction-led demand, although much of this is likely to remain within secured estates.
Elsewhere, opportunities are more selective. Markets dominated by a single defence occupier or secure government estate typically offer a narrower occupier base and greater leasing risk, while highly specialised or remote requirements may require additional capital expenditure and longer lease commitments.
Investment Implications
Defence is unlikely to become a primary source of occupational demand for IOS. Nevertheless, rising defence expenditure has the potential to become a meaningful supplementary demand driver, particularly for secure low-density industrial assets that combine buildings with operational yard space.
Not all defence-led locations offer the same investment profile. Markets dominated by a single defence occupier or secured estate may lack re‑letting flexibility, limiting liquidity and increasing asset risk. Some outdoor storage required for defence uses may be in remote locations. These more remote sites with more bespoke requirements – such as enhanced security measures, may not have multiple uses and therefore a long lease will be crucial, particularly if the site requires capex to get it up to user requirements.
For investors, the most attractive opportunities are likely to be found in markets where defence activity strengthens existing industrial and logistics fundamentals rather than acting as a standalone investment case. Locations with diverse occupier bases, strong infrastructure and established industrial ecosystems are expected to offer the best combination of demand depth, income resilience and liquidity.
Sign up to Knight Frank Research.
