

UK Hotel Sector Continues to Deliver Growth Despite Rising Cost Pressures
16 November 2026

The UK hotel sector maintained positive momentum during Q3 2026, with both the Central London and Regional UK markets reporting revenue growth. However, performance moderated compared with the first half of the year as hotels faced tougher year-on-year comparatives, following a relatively soft start to 2025. Regional hotels outperformed the capital, achieving RevPAR growth of 3.9% compared with 1.3% in Central London, supported by resilient demand and ADR growth across all segments.
The drivers of revenue growth differed across the UK market. In Central London, Select Service hotels benefited from occupancy gains, while Luxury hotels achieved the strongest ADR growth. Across the regional market, revenue growth was driven primarily by rate growth, with ADR increases exceeding inflation in all segments except Select Service, where both occupancy and ADR growth supported performance. Occupancy across the wider regional market remained stable and close to historical highs.
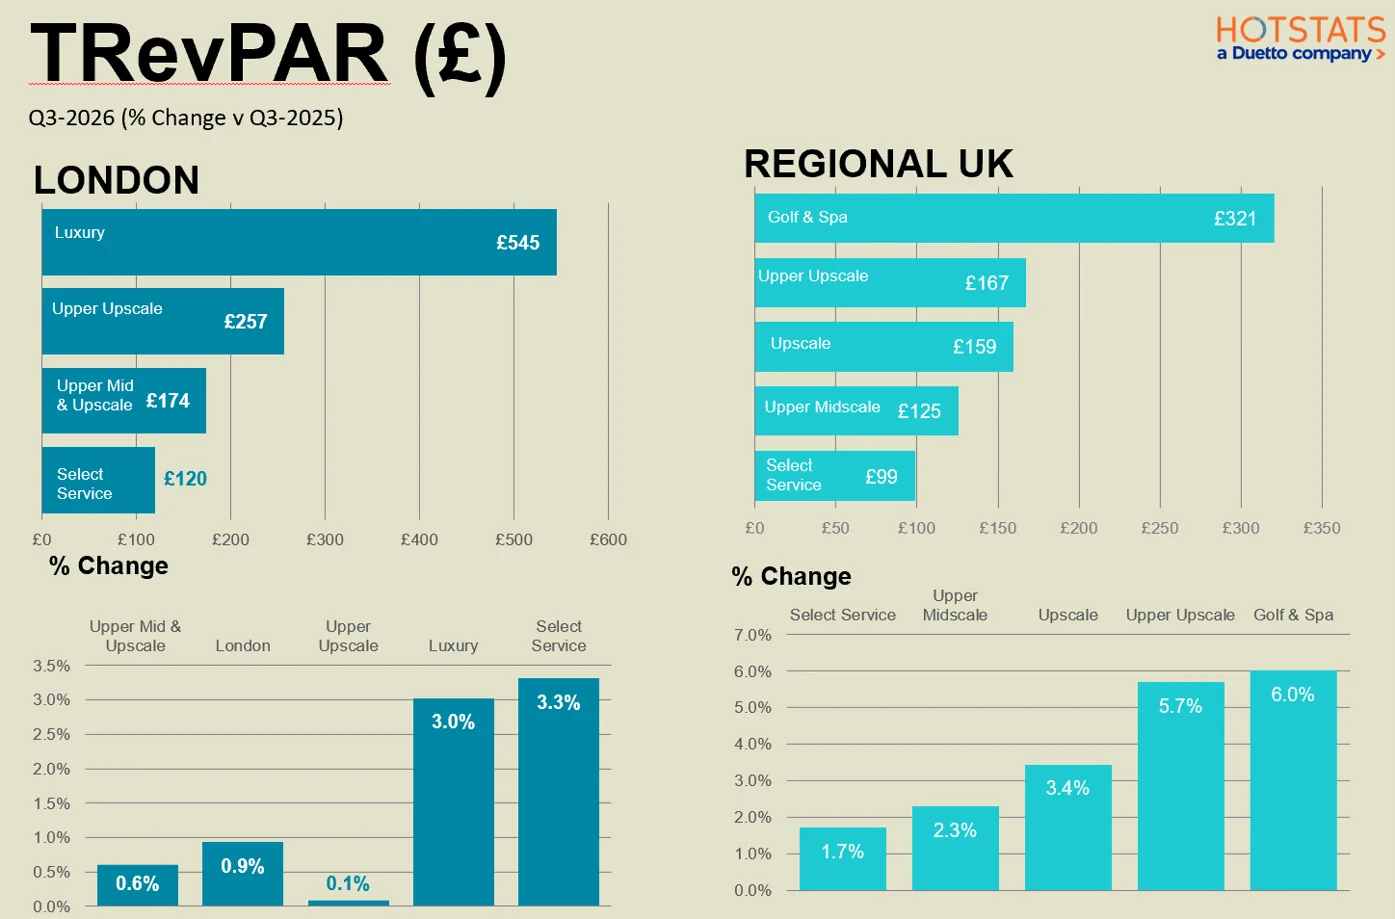
In Q3, cost pressures remained a key challenge for operators. The increase in the National Living Wage continued to drive payroll inflation, while utility costs rose sharply, particularly in Central London, where utility expenses increased by 12.7% year-on-year on a per occupied room basis. Utility cost growth was most pronounced within the Luxury segment, reflecting their higher energy consumption and service intensity. Nevertheless, disciplined labour management and cost control helped preserve margins, supporting profitability across both Central London and Regional UK hotels.
Although cost control measures helped preserve margins across much of the market, profit growth in Q3 was not universal. In Central London, Select Service and Luxury hotels translated revenue gains into higher profits, whereas Upper Upscale hotels were unable to offset cost inflation due to weaker revenue growth. As a result, GOPPAR across the wider Central London market declined by 0.6% year-on-year.
In the regions, profit growth remained stronger overall, although performance varied considerably by segment. Upper Upscale and Golf & Spa hotels delivered the strongest results, recording GOPPAR growth of 9.9% and 7.9% respectively in Q3, supported by robust ADR growth and modest margin expansion despite ongoing cost pressures. By contrast, Select-Service, Upper-mid and Upscale hotels operated in a more challenging environment, where cost increases outpaced revenue growth, limiting GOPPAR growth. Overall, the regional UK market achieved GOPPAR growth of 3.8% during the quarter and remains 5.1% ahead of the corresponding period in 2025 on a September year-to-date basis.
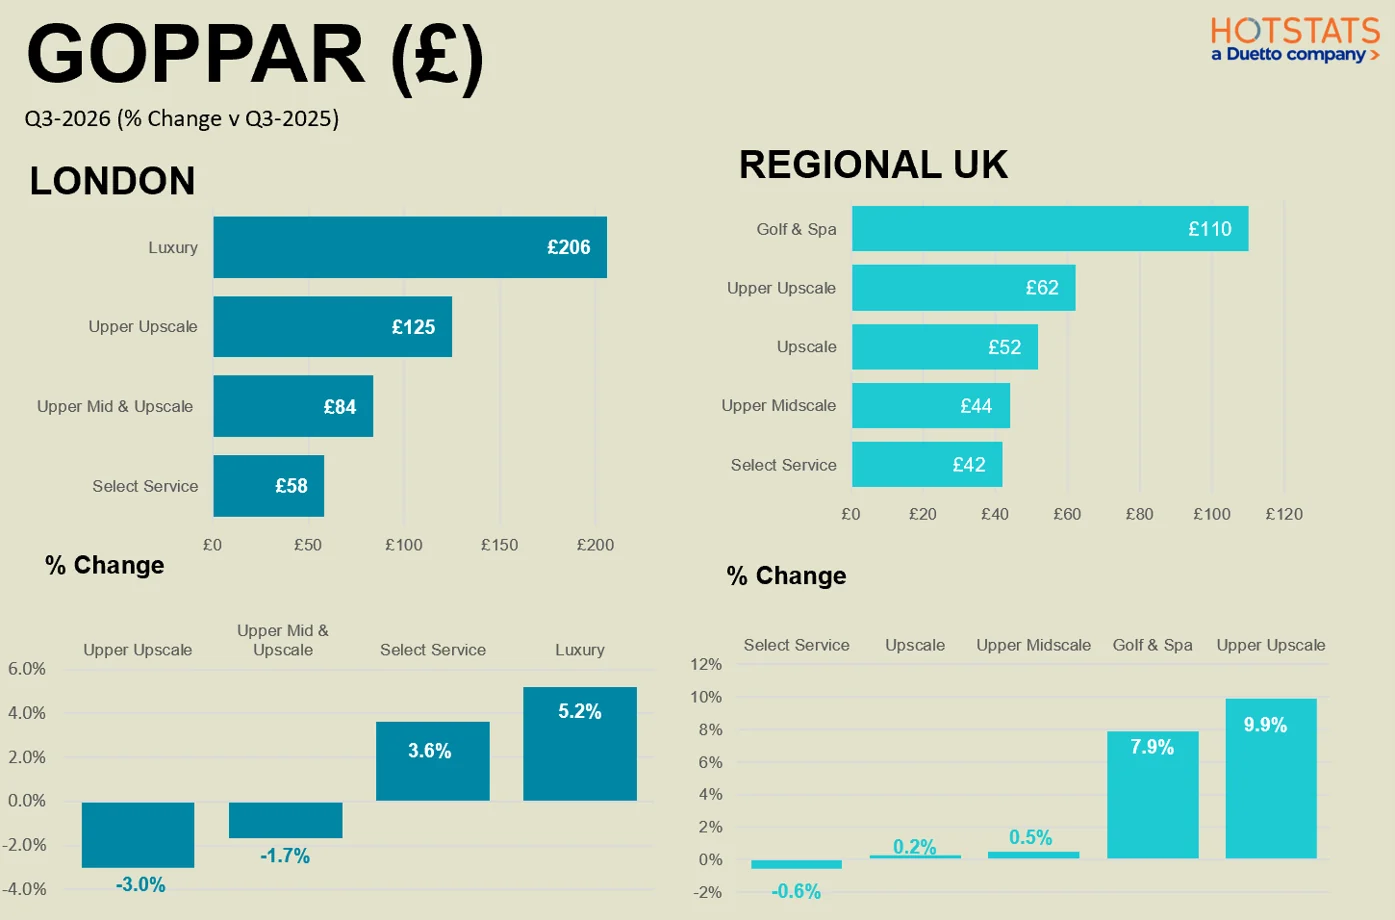
Q3 results demonstrate the resilience of the UK hotel sector but also highlight the growing divergence in performance between segments. Hotels with strong pricing power and effective cost control were better able to protect profitability from rising operating costs, while others struggled to offset inflationary pressures. With cost inflation showing little sign of easing, the ability to grow revenues at a rate sufficient to absorb rising operating costs will remain a key driver of profitability through the remainder of the year.
Download the dashboard for in-depth analysis.
Sign up to Knight Frank Research
