
Robust investment so far this year has been led by a handful of large operational deals
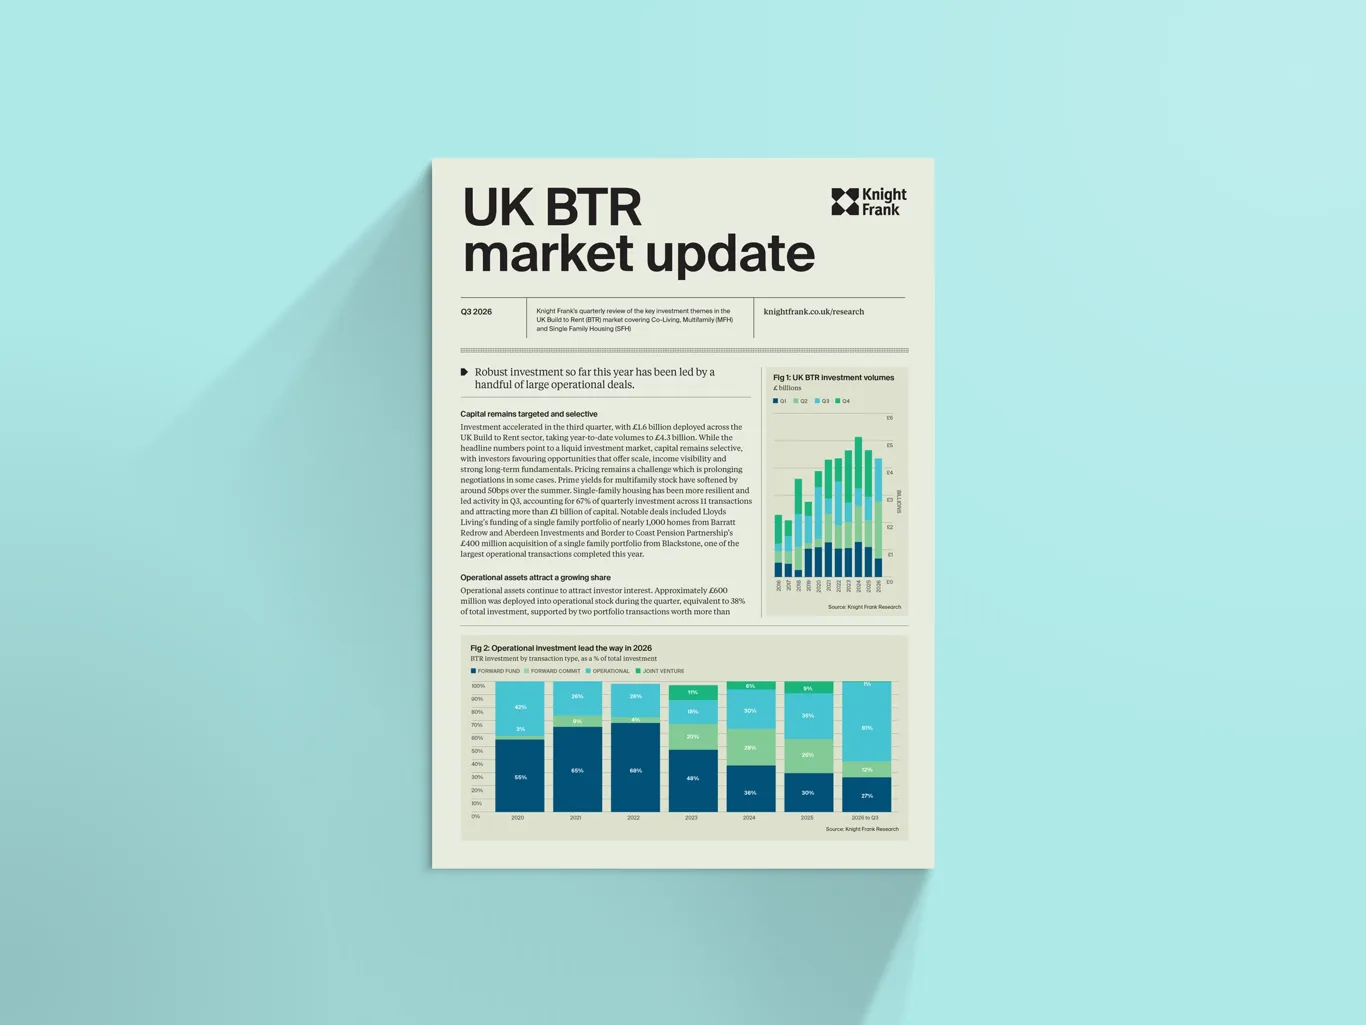
UK BTR market update Q3 2026
27 October 2026
Capital remains targeted and selective
Investment accelerated in the third quarter, with £1.6 billion deployed across the UK Build to Rent sector, taking year-to-date volumes to £4.3 billion. While the headline numbers point to a liquid investment market, capital remains selective, with investors favouring opportunities that offer scale, income visibility and strong long-term fundamentals. Pricing remains a challenge which is prolonging negotiations in some cases. Prime yields for multifamily stock have softened by around 50bps over the summer. Single-family housing has been more resilient and led activity in Q3, accounting for 67% of quarterly investment across 11 transactions and attracting more than £1 billion of capital. Notable deals included Lloyds Living’s funding of a single family portfolio of nearly 1,000 homes from Barratt Redrow and Aberdeen Investments and Border to Coast Pension Partnership’s £400 million acquisition of a single family portfolio from Blackstone, one of the largest operational transactions completed this year.
Operational assets attract a growing share
Operational assets continue to attract investor interest. Approximately £600 million was deployed into operational stock during the quarter, equivalent to 38% of total investment, supported by two portfolio transactions worth more than £500 million combined. Stabilised assets have now accounted for 61% of year-to-date investment, reflecting both challenges in the funding market and investor demand for established income, proven operational performance and immediate scale. Against the current macro backdrop, operational portfolios and platforms are becoming an increasingly important route through which investors can access rental income while limiting development and delivery risk. An increase in large-scale operational portfolio transactions has also resulted in deal sizes increasing, averaging £96 million so far in 2026 up from £64 million last year.
Single-family housing takes a growing share
The UK’s BTR stock now comprises 173,399 completed homes, up 22% year-on-year, with a further 47,105 under construction and 125,932 in the planning pipeline. Apartment-led multifamily development continues to account for the majority of delivery, representing 68% of homes under construction. However, single-family housing continues to expand and now makes up more than a quarter of all BTR homes being built. This shift is likely to continue given the regulatory, cost and geopolitical pressures which are impacting urban multifamily development.
Your First Home – a rising tide lifts all ships?
The Government’s proposed introduction of targeted first-time buyer support through its Your First Home scheme could provide a meaningful boost to housing delivery, subject to the final design. While not a direct replacement of Help to Buy, the previous programme supported 328,000 first-time buyer purchases between 2013 and 2023 and, at its peak, accounted for around 30% of new-build sales. Although details of house-price caps and income thresholds remain outstanding, a well-targeted scheme could improve affordability, support first-time buyer demand and encourage development activity, albeit to a lesser extent than previous support.
For the BTR sector, the policy could reduce some developers’ reliance on bulk sales over time, particularly among housebuilders delivering the most affordable product where first-time buyer demand is strongest. Any impact on institutional acquisition opportunities is likely to be gradual, however, reflecting the time required for changes in land acquisition and development strategies to feed through. Bulk sales are also now a more established part of housebuilder delivery models, with SFH increasingly viewed as a strategic route to market rather than simply a response to weaker private sales. Its ability to accelerate delivery and de-risk larger sites should therefore remain attractive, even alongside targeted first-time buyer support.
Private landlord exits deepen the rental supply gap
Regulatory change continues to reshape the UK rental market, providing a supportive backdrop for institutional investment. Rising compliance costs, tax changes and more demanding operational requirements have contributed to the sustained exit of smaller private landlords. Knight Frank analysis indicates that at least 477,000 homes have been sold by landlords since 2014, around 90% of which were subsequently purchased by owner-occupiers and removed from the private rented sector. Even accounting for BTR completions over this time, the result has been a sustained net loss of rental housing.
Rental growth under the RRA
For multifamily investors, early evidence suggests that the impact of the Renters’ Rights Act may be more manageable than initially feared. Data from Knight Frank’s lettings office network shows that some 35% of landlords have delayed rent reviews rather than initiate the Section 13 process, while 35% of notices served have subsequently resulted in a lower increase being agreed with the tenant. However, tribunal decisions have generally been swift and supportive of rent increases where robust market evidence has been provided, which lends itself to the BTR model where comparable evidence within buildings is easily accessible. Tenant mobility has also increased, with tenants initiating 72% of tenancy terminations since May, reflecting the shift in control envisaged by the legislation. Taken together, the findings suggest that rental growth remains achievable under the new framework, particularly for operators with the scale, data and operational expertise to evidence market rents and navigate the revised regulatory environment.
Research
We like questions, if you've got one about our research, or would like some property advice, we would love to hear from you.
BTR
Valuation, Capital Advisory and Planning
Recent Living Sectors Research
Build-to-rent and Multifamily
Build to Rent Market Update
Knight Frank’s quarterly review of the key investment themes in the UK Build to Rent (BTR) market.
27 October 2026
Land & Development
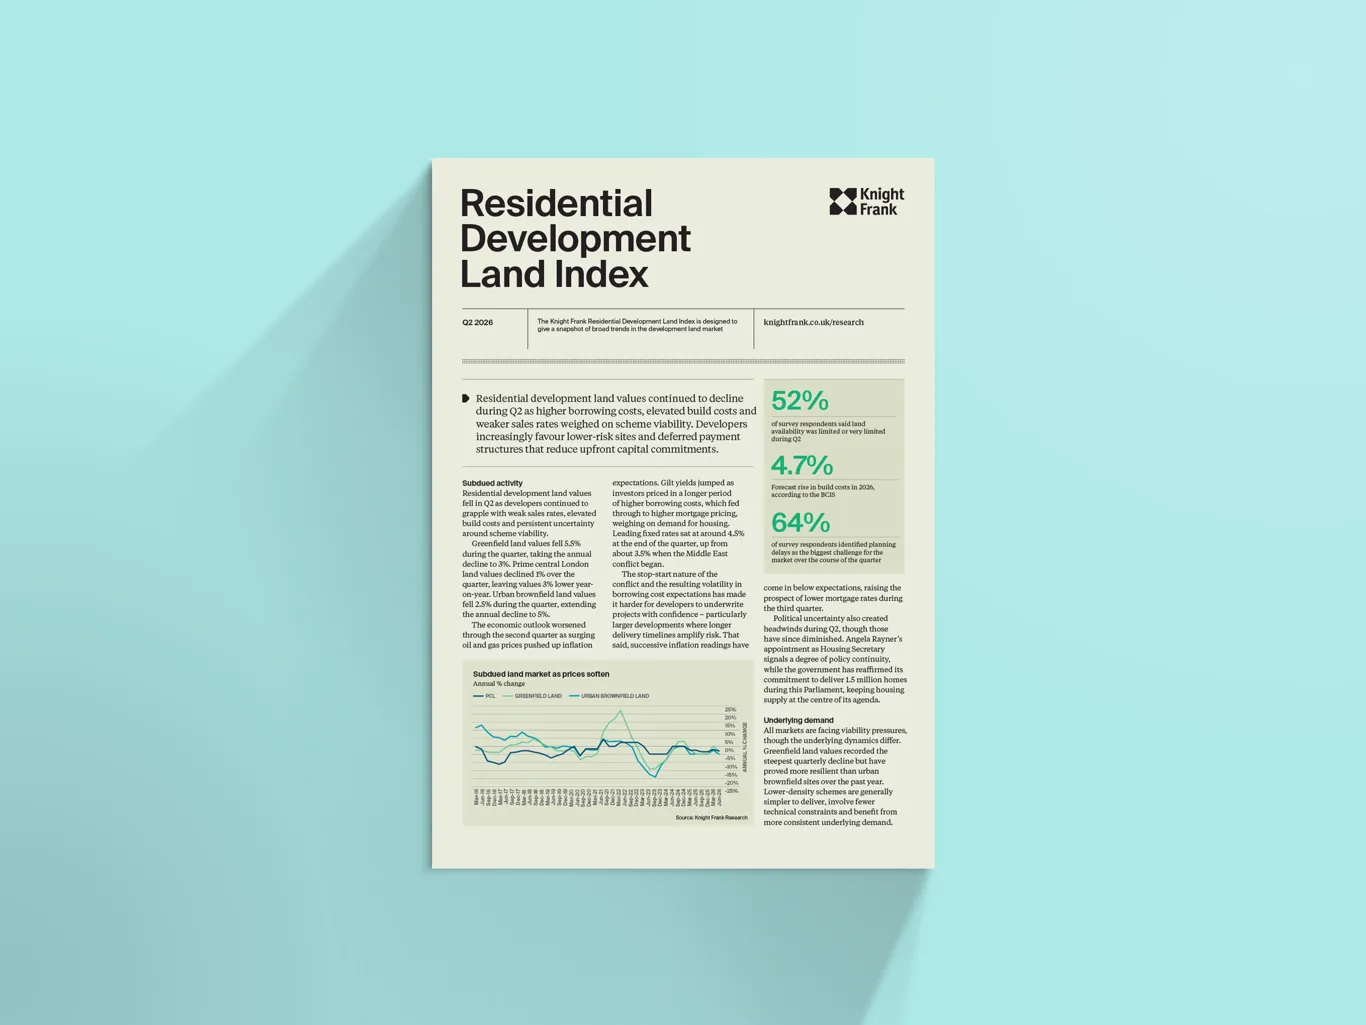
UK Res Dev Land Index
Knight Frank’s Residential Development Land Index tracks the performance of residential land values across prime central London and England each quarter.
12 August 2026
Build-to-rent and Multifamily
Single Family Housing Report
Knight Frank’s review of the performance and opportunities in the nascent SFH to rent sector.
14 July 2026
Build-to-rent and Multifamily
Multifamily
UK multifamily remains resilient amid shifting macro conditions. This report examines investment trends, policy opportunities, and rental dynamics, alongside insights from our OpEx database and operational performance survey.
06 March 2026
Prime residential
The Residence Report
The global perspective on luxury residential development
08 September 2025
Towards a New London Plan
16 July 2025
Build-to-rent and Multifamily
Build to Rent Resident Experience Index
Our Build to Rent Resident Experience Index measures the lived-experience for residents in BTR schemes, and identifies what “best-in-class” looks like.
11 September 2024
Land & Development
Co-Living Report
Our Co-Living report outlines the opportunity for funders and developers to capitalise on the solid near-term and projected long-term demographic trends underpinning the rapid growth of the sector, as well as providing a detailed analysis of the development pipeline.
03 July 2024
Land & Development
Affordable Housing Report
In this report, we assess the state of the UK affordable housing sector. A slowdown in housing delivery comes against the backdrop of a long-term need for more housing of all tenures, but particularly for affordable housing.
20 June 2024
Land & Development
South East Residential Development Review
Knight Frank's review of the key development and investment themes in the South East land market
29 November 2023
Land & Development
Focus on: Hammersmith & Fulham
This report provides a detailed analysis of the residential market in Hammersmith & Fulham. The report examines market dynamics, demand and the development pipeline.
27 June 2023
Sign up to Knight Frank Research.
